Phone 248.871.7756 | Email info@gmedicareteam.com
Watch Videos on 
 Search
 Search
IRMAA stands for Income-Related Monthly Adjustment Amount. It's an extra charge added to your Medicare Part B premium, and to your drug coverage, when your income is above a certain level.
It is not a penalty, and it doesn't mean you did anything wrong. It is simply how Medicare prices Parts B and D for higher earners. Roughly 8% of people on Medicare pay it.
Social Security looks at your tax return from two years earlier. Specifically, your modified adjusted gross income (MAGI): your adjusted gross income plus any tax-exempt interest.
Social Security sends a letter if you owe IRMAA. The amount is usually taken out of your Social Security check along with your Part B premium.
Here are the 2026 charts showing the income levels and related IRMAA amounts. They're based on your 2024 tax return, and they're per person: if you're married and both on Medicare, you each pay.
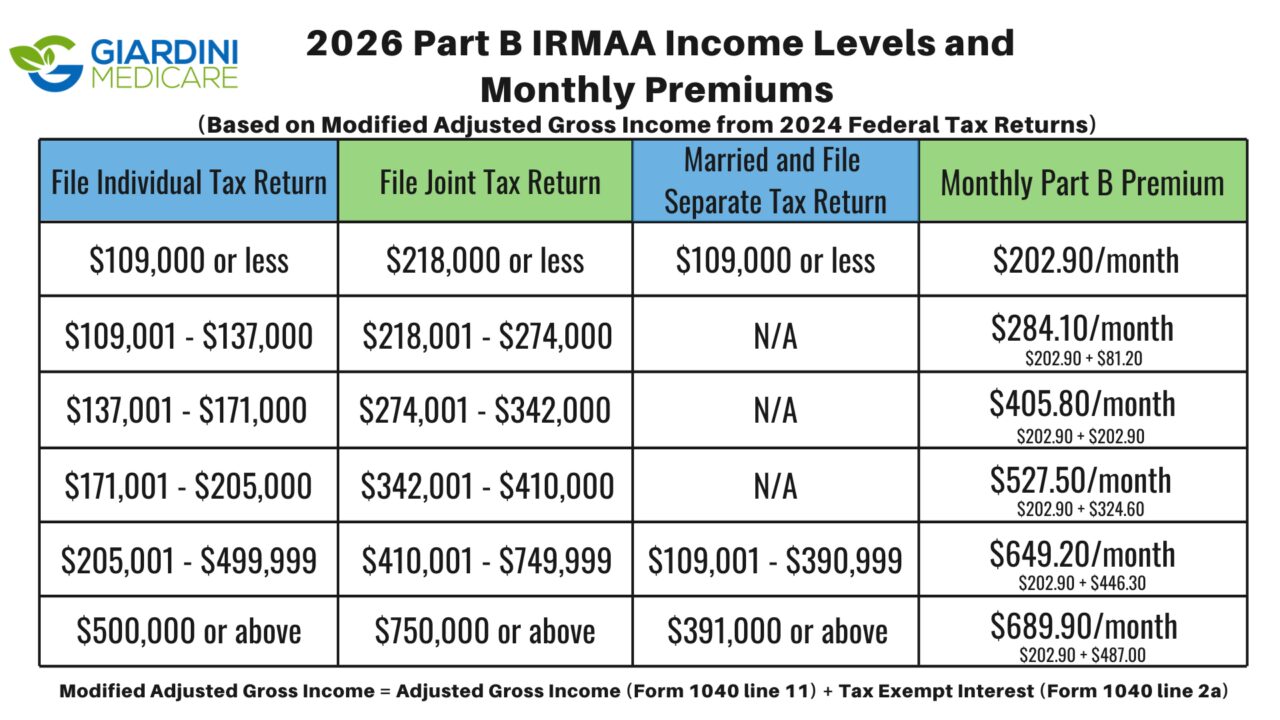
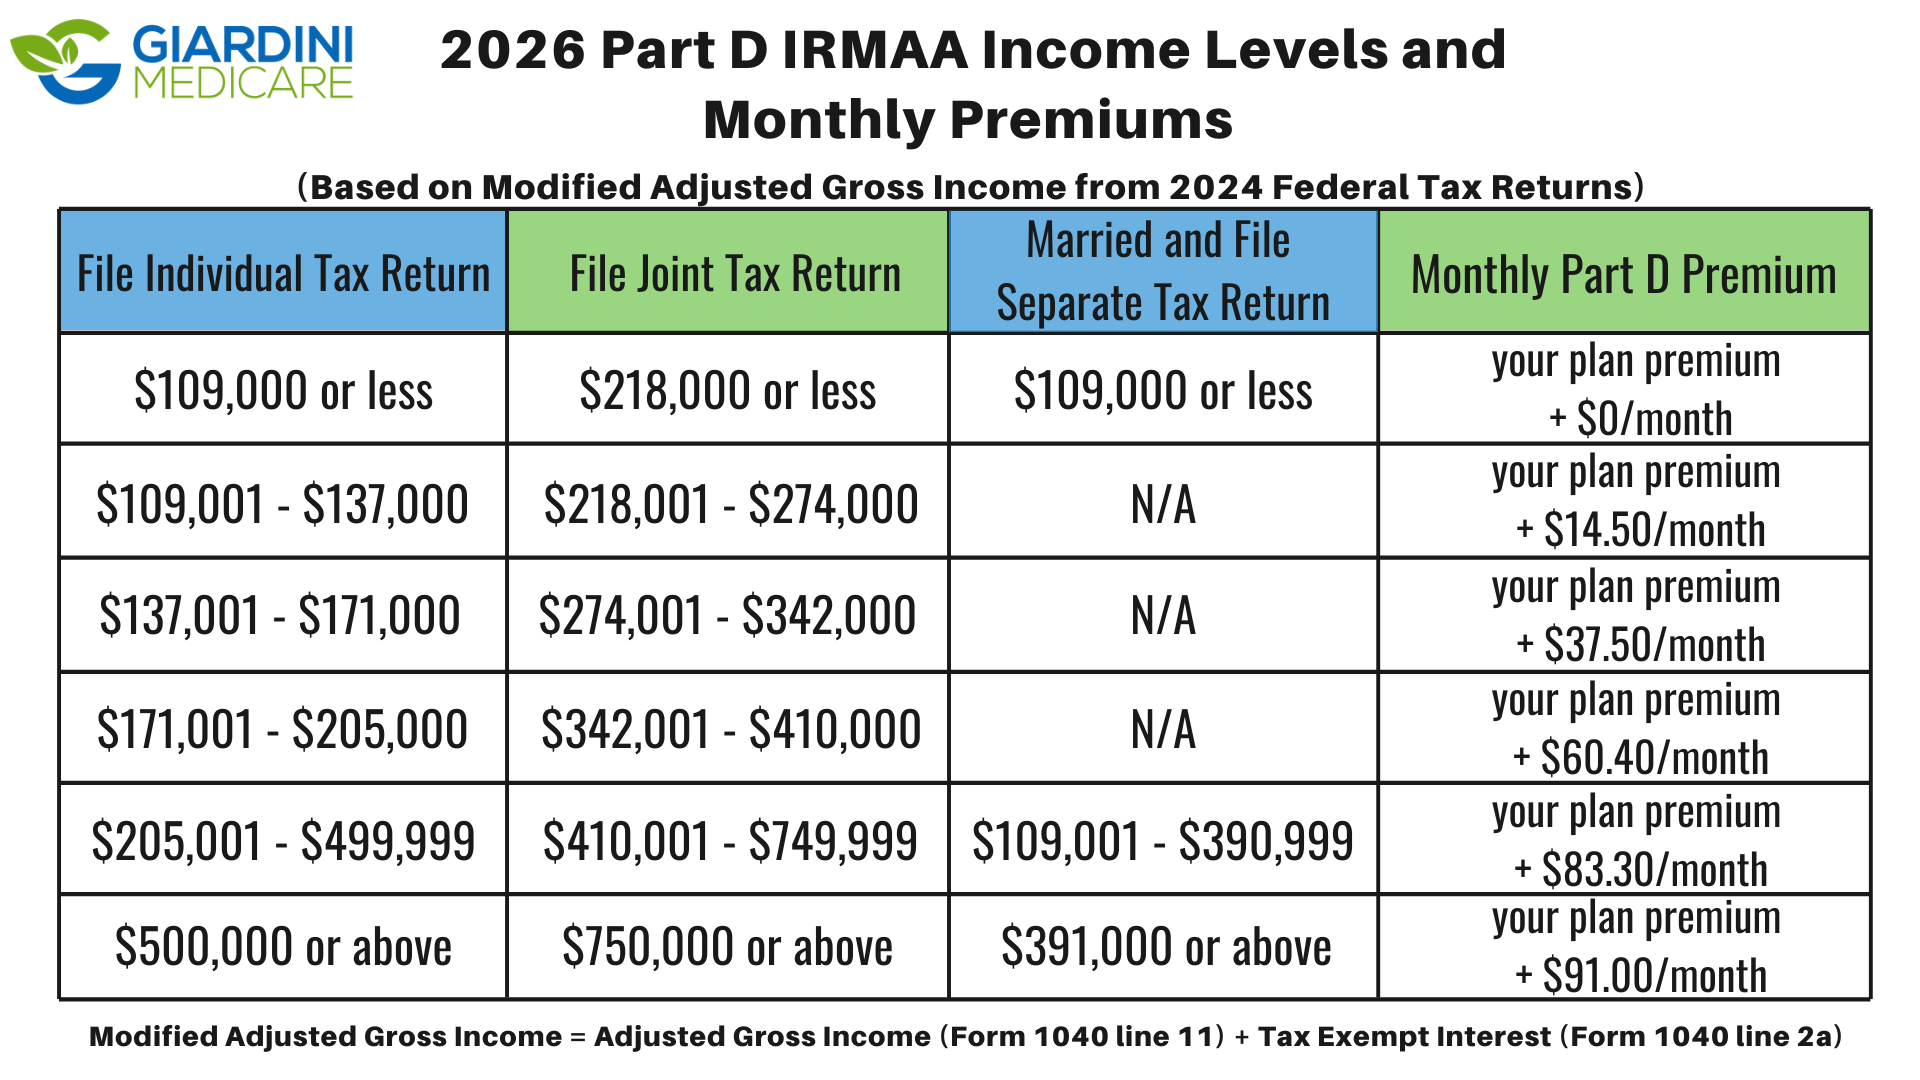
Tap a chart to open it full size. The Part D amount is added on top of your drug plan's own premium. Source: CMS 2026 Medicare Parts A & B Premiums and Deductibles fact sheet.
The two-year lookback is why IRMAA catches so many new retirees. Your 2024 income may have included a full salary you no longer earn. If a life-changing event lowered your income, you can ask Social Security to use a more recent year with form SSA-44.
Qualifying events:
You file the SSA-44 with Social Security, along with proof of the event and your income (for example, a letter from your former employer and your estimate for the current year). If they approve it, your IRMAA is lowered or removed.
If you filed an amended return, or the income Social Security used is simply incorrect, contact Social Security and ask for a new initial determination using the corrected information.
Roth conversions, selling a home or investments, and large IRA withdrawals can all push you into a higher bracket two years later. Your tax professional or financial advisor can help you time these. We're not CPAs, so please run the numbers with them.
IRMAA raises your Part B. It doesn't touch your Medigap price.
See exactly what Plan G, Plan N and the HDG Combo cost where you live, in about two minutes.
Get your price at ComboQuotes.comWe don't require an email or phone number to get information.